

Payday Cash Advance TriceLoans
Trice Loans
- 4.7
- 192.00 Reviews
- 50.00K
- Downloads
- Free
- Price
Screenshots
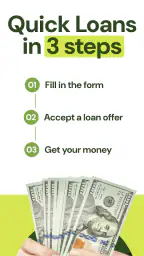
Payday Cash Advance TriceLoans Pros and Cons
Pros
- Quick application process with minimal paperwork required
- Clear repayment schedule helps users plan their budget
- May provide emergency funds when traditional credit is unavailable
- Online access makes account management convenient
- Useful for borrowers needing a small, short-term cash advance
Cons
- High fees or APR can make borrowing expensive
- Late payments may lead to additional charges and credit consequences
- Loan availability and terms can vary by location and eligibility
- Short repayment periods may put pressure on tight budgets
- Sharing financial and personal data raises privacy concerns
 Analysis by All-app
When an unexpected bill lands between paydays, the appeal of a cash-advance app is obvious: I want a quick way to check whether I can cover the gap without visiting a branch or filling out a long paper application. Payday Cash Advance TriceLoans is built around that narrow moment. It is a free finance app from Trice Loans, aimed at people looking for a short-term borrowing option and presenting itself as a fast route to an advance without a traditional credit-check emphasis.
My first impression is that this is not an app I would treat like a budgeting tool, savings account, or everyday banking replacement. Its usefulness depends on the complete borrowing journey: entering information, reviewing what is offered, understanding the repayment obligation, and making sure the money actually fits the need. That distinction matters because a quick application can still lead to an expensive or stressful decision if I focus only on speed.
From an urgent expense to a borrowing decision
I’d start with the expense itself: a cash advance is most useful when the gap is specific and the next income date is dependable, not when borrowing is becoming a routine way to cover ordinary costs. From there, I’d look at how TriceLoans frames the application and what I would need to check before treating a possible offer as a sensible solution.
The starting condition: a short gap, not a long-term solution
The most sensible use case is a temporary cash shortage with a clear repayment plan. Imagine I have a utility payment due before my next paycheck and know exactly when regular income will arrive. In that situation, an advance may appear practical because the problem is timing rather than a permanent lack of income. I would open TriceLoans to explore whether the app can connect that immediate need with a suitable offer.
I would not begin by assuming approval, a particular amount, or a particular cost. The app’s store summary emphasizes instant cash advances and no credit check, but those phrases should not replace reading the actual terms shown during the process. A lender or lending service still needs enough information to assess the request, and the final obligation is more important than the convenience of starting an application.
That is the first non-obvious trade-off: a no-credit-check approach may feel more accessible, but it does not mean borrowing is risk-free or that every applicant receives the same outcome. I would use the app to investigate an option, not to decide in advance that money is guaranteed.
What the first step feels like
The app is free to install, which lowers the barrier to looking around. It is rated for Everyone, so its presentation is intended for a broad audience, but an age label does not make a financial commitment suitable for every person. I would still keep a calculator or notes app nearby and write down the amount I actually need before beginning. Asking for more than the bill requires can make a short-term problem harder to close.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
Because the current version is 1.1.6, I would also make sure I am using the current release available for my device rather than relying on an old installation. The app supports Android 7.0 and later, which covers many older Android phones. That is useful for someone who cannot run newer finance apps, although device compatibility alone says nothing about whether the resulting offer will be affordable.
Moving through the application
The practical workflow is best approached in stages. I would start by entering only accurate personal and financial information, checking each field before moving on. A rushed typo in contact or income details can create delays later, especially when another party needs to verify or process the request. If the app asks me to pass information onward for evaluation, I would pause long enough to understand who is involved and what happens after submission.
This handoff is easy to overlook. An app can be the front door without being the final decision-maker or the organization that sends funds. For me, that means the screen where I begin is not necessarily the same place where I receive the binding terms. I would treat every transition as a fresh checkpoint rather than assuming that the app’s simple interface represents the entire lending arrangement.
Before accepting anything, I would look for the total repayment amount, the timing of payments, and any applicable charges. The app includes in-app purchases priced from $1.99 to $4.99 per item, so I would be especially careful to distinguish any app-related purchase from the cost of borrowing. Those are not interchangeable. A small-looking charge inside an app can be easy to overlook when I am focused on getting cash, while the loan obligation may be shown elsewhere in the flow.
The handoffs that deserve the most attention
A short-term advance usually involves more than one relationship: me as the applicant, the app as the interface, and the financial provider or providers handling the offer and repayment. I would not assume that installing TriceLoans creates a direct account with the developer, Trice Loans, in the same way that installing a bank’s official app creates a banking relationship. The important question is what entity presents the terms and what entity I would owe.
This is where I would save or record the final agreement before confirming. I would note the amount requested, the amount received, the total due, and the dates involved. If those details are difficult to locate or appear only briefly, that is a serious usability problem for a finance app. Speed is helpful only when the information needed for an informed decision remains visible.
Another useful habit is to separate “eligible to continue” from “safe for me to accept.” An application may move forward while the repayment still clashes with rent, food, transport, or other fixed commitments. I would compare the expected repayment with the next paycheck after essential expenses, not with the paycheck’s headline amount. That simple check is more valuable than any promise of instant processing.
What happens after submission
Once the information is submitted, the outcome may depend on the review and the provider connected to the request. I would expect the app to guide me toward a result, but I would not plan a same-day bill payment until the money is actually available. A common mistake with cash-advance services is treating an application confirmation as if it were a deposit.
If an offer appears, I would read it from the repayment side first. How much leaves my account, and when? Can I meet that date without taking another advance? Does accepting it solve the original problem, or does it move the problem into the next pay cycle? These questions turn a fast interface into a deliberate financial decision.
If the request does not produce a usable offer, I would close the process rather than repeatedly submitting applications in frustration. The app’s promise of accessibility may make it attractive to people who have difficulty with conventional credit, but repeated short-term borrowing can create a cycle in which each paycheck is already committed before it arrives. TriceLoans can be a place to explore an option; it should not become the automatic response to every cash shortage.
The result: useful when the numbers line up
In the best-case scenario, the app helps me move from a defined, temporary need to a clearly understood advance. Its strongest point is convenience. I can investigate a payday-style cash option from an Android phone, without treating a branch visit or a traditional credit inquiry as the only route. That is particularly relevant when the expense is urgent and the usual alternatives are slow or unavailable.
The audience response suggests that many people find the concept useful: the app holds a 4.7 average from around seven thousand ratings and has passed fifty thousand installs. Those figures indicate meaningful interest, although they do not tell me whether an individual offer will be affordable or whether the app fits a particular financial situation. I see the rating as evidence of a generally positive user experience, not as a substitute for reading loan terms.
For a realistic example, suppose I need to bridge a small grocery or transport shortfall until my next confirmed income date. I would enter the process with a fixed ceiling, reject any offer that exceeds what I can repay after essentials, and keep a record of the agreement. If the numbers work, the app may be more convenient than calling several lenders or waiting for a conventional application. If the numbers do not work, the correct result is to walk away, even if the application itself was quick.
Where the usual alternatives may be better
Compared with a credit union, bank overdraft facility, employer advance, or a carefully planned emergency fund, a payday-style app may be easier to approach but less suitable for repeated use. A bank or credit union may offer a more established relationship and clearer account history, while an emergency fund avoids borrowing costs altogether. An employer-based option may also align repayment with payroll in a way that creates less uncertainty.
Those alternatives are not always available, which is why an app like this can still have a legitimate place. Someone with limited access to conventional credit may value a digital application that focuses on speed and accessibility. Even then, I would compare the complete repayment obligation rather than choosing based on the fastest screen or the most reassuring wording.
TriceLoans is also not the right choice for someone who needs a large, long-term loan, wants detailed spending analysis, or expects the app to repair an ongoing budget deficit. Its identity is tied to short-term cash access. For long-term debt, a regulated lender with transparent installment terms and independent advice would be a better direction. For recurring shortfalls, a budget review or conversation with a creditor may solve more than another advance.
Where the flow breaks down
The biggest friction is the gap between a simple promise and a complicated financial outcome. “Fast” describes the intended experience, but it does not guarantee that every handoff, review, or transfer will be immediate. I would be uncomfortable if the app made the request feel effortless while placing repayment details behind several screens or presenting charges without enough context.
The no-credit-check positioning can also create the wrong expectation. It may attract applicants who believe their financial history no longer matters, yet affordability still matters enormously. A person with irregular income, existing advances, or no realistic repayment date should be cautious. The absence of a conventional credit check does not remove the consequences of missing the obligation.
There is also a practical cost to using any short-term advance: it can solve today’s timing issue by reducing flexibility in the next pay cycle. My advice is to decide the maximum acceptable repayment before viewing an offer. That prevents the emotional pressure of an urgent bill from setting the amount for me. I would also avoid paying for optional in-app items while trying to preserve cash for essentials; the listed purchase range makes that distinction worth keeping in mind.
Finally, I would not install the app expecting a full financial safety net. It does not replace a written budget, a savings buffer, or a conversation with a bill provider about an extension. If the need is recurring, the app may only postpone the underlying issue. The most responsible workflow ends with a repayment plan that works without another advance.
My recommendation after following the full workflow
I see Payday Cash Advance TriceLoans as a focused tool for a narrow situation: a person has a short, clearly defined cash gap and wants to explore a digital payday-advance route. The free download, broad age rating, older Android support, and strong user rating make it approachable. The developer, Trice Loans, has kept the product’s purpose direct rather than presenting it as a general-purpose money manager.
My recommendation is conditional. I would consider using it only after confirming the provider, the total repayment, the due date, and the effect on my next paycheck. I would never treat an application result as guaranteed funds, and I would not accept an offer simply because it arrived quickly. The app is most useful when it supports a decision I have already bounded with real numbers.
The key test is simple: if I cannot explain exactly how and when I will repay the advance, I should not accept it. Used with that discipline, TriceLoans may help someone investigate a temporary option during a tight week. Used as a recurring fix for an income problem, it is likely to add pressure rather than remove it. That balance—convenient access on one side, careful repayment planning on the other—is the part of the experience I would want a friend to understand before installing Payday Cash Advance TriceLoans.
At its best, Payday Cash Advance TriceLoans shortens the distance between an urgent expense and a possible short-term solution. Its real value is not the speed of the first tap, but whether the complete journey ends with terms I understand and a repayment date I can genuinely meet.
Frequently Asked Questions
What is Payday Cash Advance TriceLoans, and how does it work?
Payday Cash Advance TriceLoans is presented as a short-term borrowing service that may help users request money before their next payday. After providing personal, employment, income, and banking information, applicants may receive an eligibility decision and loan offer from a participating lender. The service may connect borrowers with third parties rather than lend money directly, so approval, fees, repayment dates, and interest can vary.
Can everyone qualify for a loan through Payday Cash Advance TriceLoans?
No. Using the service does not guarantee approval or access to a specific amount of money. Eligibility can depend on factors such as age, residency, employment, regular income, an active bank account, and the lender’s own underwriting requirements. Some applications may be declined, while approved users may receive different terms. Review the offer carefully and confirm that the lender operates legally in your location.
How much does a Payday Cash Advance TriceLoans loan cost?
The cost depends on the lender and the terms shown in the final agreement. A short-term loan may include interest, origination charges, service fees, late-payment fees, or other costs, and its annual percentage rate can be significantly higher than that of conventional credit. Before accepting, check the total repayment amount, payment schedule, and all disclosures rather than focusing only on the amount deposited.
When will the money arrive, and how is repayment handled?
Funding and repayment timing are determined by the lender, your bank, the application time, and whether additional verification is required. Some approved requests may be deposited quickly, but same-day funding should not be assumed. Repayment may be scheduled as a single withdrawal or several installments from your bank account. Make sure sufficient funds are available and understand how to change or cancel payment arrangements.
Is Payday Cash Advance TriceLoans safe to use?
Treat the service as a financial application and review it carefully before submitting sensitive information. Check the privacy policy, permissions, lender disclosures, contact details, licensing information, and the identity of any company making an offer. Never pay an upfront fee to “guarantee” approval, and avoid sharing passwords or security codes. Compare alternatives such as a bank, credit union, employer advance, or local assistance program.


